This chapter is a template. It shows prose, maths, numbered theorems, sidenotes, callouts and executed code in one place. Delete it once you have real notes.
1 Setup
Let X_1, X_2, \dots be independent and identically distributed with mean \mu and finite variance \sigma^2. Write the sample mean as
The law of large numbers says \bar{X}_n \to \mu. The central limit theorem describes the fluctuations around that limit.1
Definition 1 (Convergence in distribution) A sequence Y_n converges in distribution to Y, written Y_n \xrightarrow{d} Y, if F_{Y_n}(y) \to F_Y(y) at every point y where F_Y is continuous.
Theorem 1 (Central limit theorem) With \bar{X}_n as in Equation 1,
Proof. Sketch. Standardise so that \mu = 0 and \sigma = 1, and let \varphi be the characteristic function of X_1. Then \varphi(t) = 1 - t^2/2 + o(t^2), so
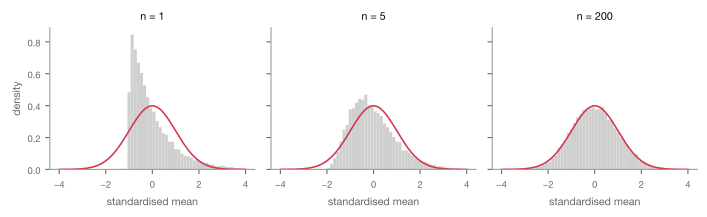
Figure 1: Standardised sample means of Exponential(1) draws against the standard normal density.
3 Exercises
Repeat the experiment with a Bernoulli(0.01) distribution. How large must n be before the histogram looks normal?
Replace the exponential with a standard Cauchy. What happens, and which hypothesis of Theorem 1 fails?
Footnotes
Footnotes are printed in the margin on a wide screen, level with where they are referenced. On a narrow screen, hover or tap the number to read the note in a card.↩︎
A long note is cut off after nine lines with a fade, and shown in full while you hover it or its number. This one is padded to show that: the characteristic function always exists, unlike the moment generating function, which is why the proof is usually written with it. The price is a detour through complex numbers. A proof by moment generating functions is shorter to state but needs every moment to be finite, which rules out many distributions the theorem actually covers. Lindeberg’s replacement argument avoids transforms altogether.↩︎